
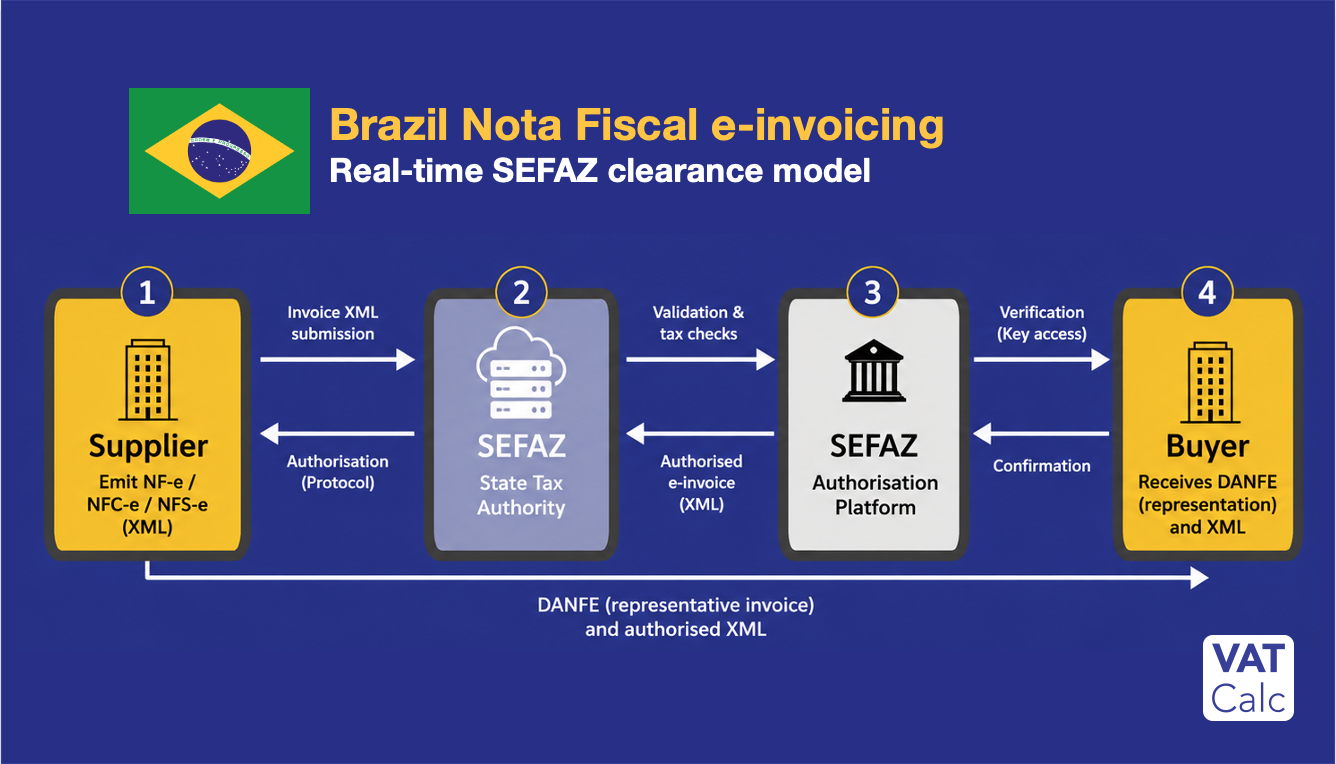
Nonresident businesses will be required to issue Brazilian electronic invoices from 1 December 2026
Brazil has published the implementation calendar for the new IBS and CBS electronic fiscal documents. This adds foreign suppliers of digital services, software and other taxable supplies into Brazil, whilst several operational details remain unclear, businesses should now assume that e-invoicing will become part of their Brazilian compliance obligations.
This is part of the 2026-32 Brazil VAT implementation.
December 2026 start date
Following the publication of Joint Act RFB/CGIBS No. 4/2026, Brazil has confirmed implementation dates for several new electronic document models supporting its IBS/CBS tax regime.
From 1 December 2026, the following are expected to become mandatory:
- NF-e for IBS/CBS taxpayers that are not registered under the existing ICMS regime.
- NFS-e for digital platforms, covering both platform fees and marketplace transactions.
- NFS-e for intangible goods, including software, digital products and other intangibles.
Although the Joint Act does not explicitly mention foreign businesses, earlier IBS/CBS regulations issued in April 2026 introduced the principle that nonresident entities making taxable supplies in Brazil must issue electronic invoices in accordance with Brazilian tax authority requirements.
Taken together, the measures strongly suggest that foreign suppliers will fall within these new obligations from December.
Technical specifications due in September 2026
The tax authorities expect to publish the technical layouts for these new invoice models by 1 September 2026. Brazil has also announced a temporary relaxation under which invoices will not initially be rejected if the new IBS/CBS fields are left blank whilst the validation rules are finalised.
That should give businesses additional time to update ERP systems, billing platforms and e-invoicing solutions before full validation is enforced.
Uncertainty on which transactions in scope
Despite the clearer timeline, several practical issues are still unresolved for nonresident businesses.
The authorities have yet to confirm:
- which foreign transactions will trigger IBS/CBS obligations;
- how nonresident businesses will register;
- whether overseas suppliers will use the standard Brazilian NF-e process or a simplified model;
- how invoices will be transmitted and validated from outside Brazil.
Further regulations are expected during September.


