
Finance Bill (No. 2) 2026 provides the legislative framework for mandatory B2B e-invoicing and digital VAT reporting
9 October 2026: Ireland has moved its planned B2B e-invoicing and digital VAT reporting regime into legislation with the publication of Finance Bill (No. 2) 2026.
The detailed technical specifications will follow in regulations. The final mandate is likely to include Peppol Network backbone – but this is not yet included in the legislation.

Proposed VAT B2B & B2G e-invoicing & real-time reporting
The phased rollout remains:
- 1 November 2028: VAT-registered businesses managed by Revenue’s Large Corporates Division and established or fixed-established in Ireland must issue structured e-invoices for domestic B2B transactions and report relevant invoice data to Revenue.
- 1 November 2028: all Irish businesses must be capable of receiving structured e-invoices.
- 1 November 2029: the domestic mandate extends to VAT-registered businesses engaged in intra-EU B2B trade.
- 1 July 2030: EU ViDA e-invoicing and digital reporting applies to intra-EU B2B transactions.
For the purposes of the November 2028 phase one, a business will be considered a large corporate if it is:
- a VAT-registered business whose tax affairs are managed by Large Corporates Division in Revenue; and
- established or has a fixed establishment in Ireland.
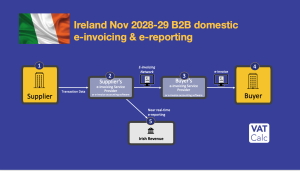
As expected the Irish regime is to be based on the EU’s EN 16931 standard, with Peppol Network exchange with 5-corner model between businesses of structured electronic invoices.
Ireland is building reporting into e-invoicing
The new legislation confirms that this is not simply an invoice-format mandate.
The framework provides for mandatory structured electronic invoices and electronic reporting of prescribed transaction data to Revenue. It also addresses customer identification, retention of structured invoices, business controls and reliable audit trails.
Specific provisions cover areas including self-billing, credit and debit notes and certain domestic reverse-charge transactions.
The detailed technical specifications will follow in regulations.
EN 16931 structured invoices
Revenue has already confirmed that invoices must comply with European standard EN 16931. PDFs and scanned invoices will not qualify as structured e-invoices.
Ireland is also working with the Irish Peppol Authority as it prepares for a substantial expansion of electronic invoice exchange.
The bigger challenge starts after the invoice is sent
For businesses, the requirement will reach beyond accounts receivable.
Invoice data must be created correctly, exchanged in structured form, reported to Revenue and ultimately remain consistent with accounting records and VAT returns.
That makes reconciliation increasingly important. As tax authorities receive transaction data earlier, discrepancies between e-invoices, ERP records and subsequent VAT reporting become visible earlier too.
Ireland has deliberately given large businesses two years to prepare. The publication of the legislation means the direction is no longer merely consultative: the implementation work can begin.


