
MyInvoice e-invoicing for businesses with sales between RM3m and RM5m grace period until 31 Dec 2027
Update: 30 Aug 2026 the turnover threshold for the fourth wave (grace period until 31 December 2027) of taxpayers to adopt e-invoicing has been increased from RM1m to RM3m. This wave has already been delayed twice, and now covers businesses with turnover between RM3m and RM5m. The original mandate commenced in August 2024.
22 April 2026: new Frequently Asked Questions covering this change were issued.


Ministry of Finance delays 4th wave MyInvois e-invoicing to Jan 2027
The MyInvois phased launch is now:
- 1 August 2024: taxpayers annual turnover above RM 100 million (approx $21m;
- 1 January 2025: taxpayers with annual turnover over RM 25 million (approx $5m);
- 1 July 2025: taxpayers above RM5 million with 6-months’ soft launch;
- 1 Jan 2028: taxpayers with annual turnover between RM3 million and RM5 million with soft launch. NOTE: new taxpayers in this category are likely given an extension to 1 July 2028; and
- 1 July 2026: (now cancelled) taxpayers with annual turnover between RM500,000* and RM1 million.
*taxpayers below RM1 annual turnover are exempted from the MyInvois mandate .
Apr 2025: revised MyInvois e-invoicing guidelines and development kit; Peppol authority
On 6 April 2025, the Inland Revenue Board of Malaysia (IRBM) issued new MyInvois 2.1 guidance on the mandatory B2B e-invoicing regime which started roll out last August. The latest guidelines provide extra details certain transaction types. There is also a new software development kit, 1.0, which includes: API revisions; FX notes; changes to validation checks; and other revisions.
OpenPeppol, the coordinator of the global Peppol e-invoicing exchange network, has confirmed The Ministry of Communications and Digital of Malaysia as the country’s Peppol Authority. This government body will now take on the role of registering local businesses onto Peppol, and ensure the smooth running of the service for local parties.
Oct 2024 FAQ’s issued
On 3 October 2024, the Malaysia Revenue Board (LHDN) issued Version 4.0 of its e-invoice Guidelines.
6-month soft launch until February 2025
On 26 July 2024, LHDN granted a 6-month soft landing for its 1st August 2024 MyInvois live e-invoicing mandate. Taxpayers in the first wave (turnover above MYR 100m) will not be obliged to pre-clear their invoices from 1 August 2024. Instead, they may use current invoice formats and digitally report the transactions in a single consolidated submission by the 7th of the following month. This means the first digital transaction reporting deadline will be 7th September 2024. This optional post invoice issuance digital reporting phase will end 1 February 2025 when the penalty regime for not reporting live via MyInvois will be imposed.
Taxpayers that voluntarily start using MyInvois live reporting from 1 August will be entitled to accelerated capital allcowances on related IT spend.
This period of flexibility is expected to give a space of time sufficient for taxpayers to ensure the implementation of e-Invoicing fully which is more effective covering all aspects such as system availability, smooth business operations and change management in business.
B2B, B2C and B2G structured e-invoice live reporting
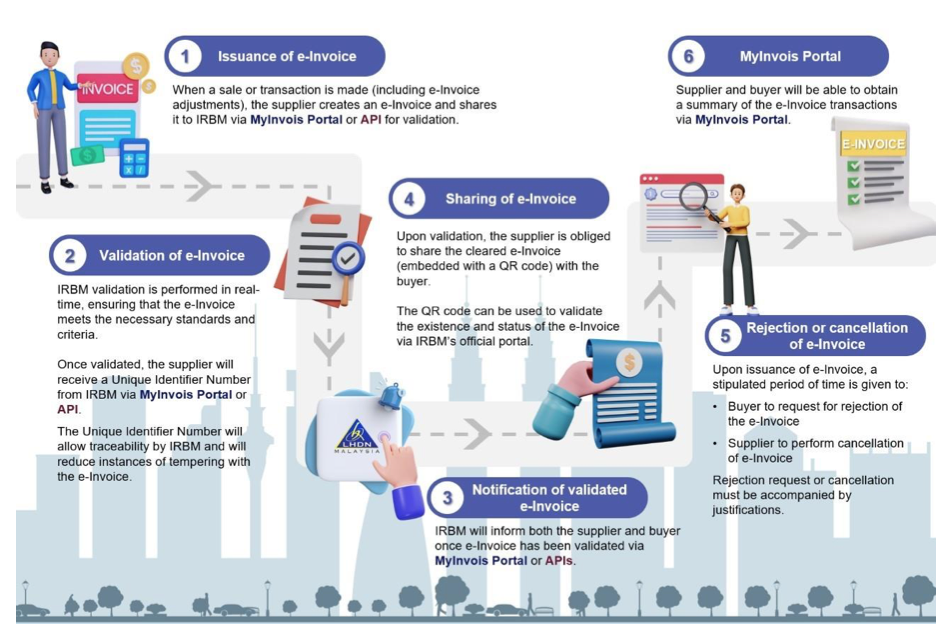
MyInvois is the portal solution of the LHDN used by taxpayers to submit their issued documents with the tax authority, get notified on events related to document issuance. This site contains documentation of the APIs exposed to taxpayer ERP systems that can be used to integrate with MyInvois System to automate the document processing. Alternatively, taxpayers may connect to LHDN’s API to submit invoices directly.
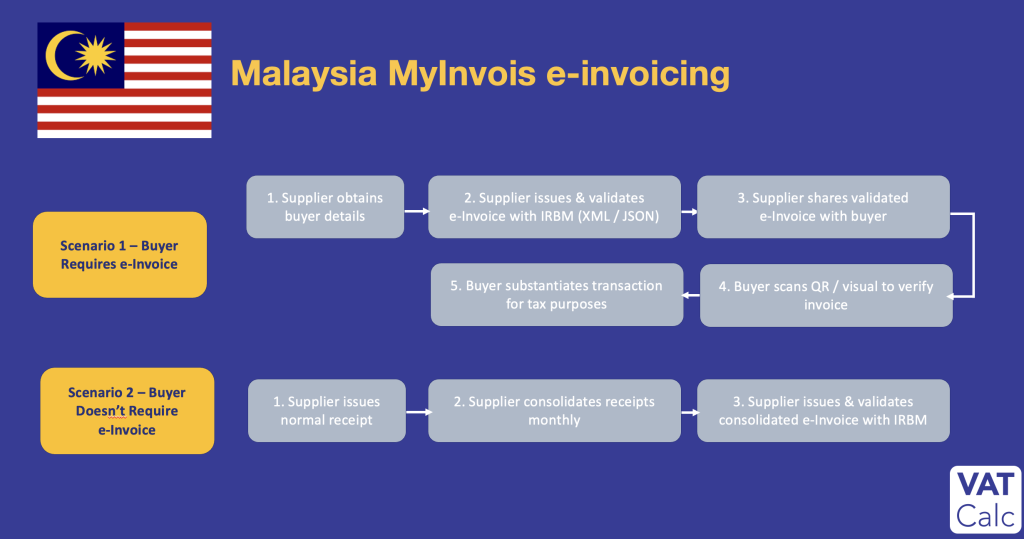
Malaysia is operating a Continuous Transaction Control CTC model, requiring sales invoices (XML) to be first sent to the tax authorities for verification via the government’s portal or API. Once approved, the invoice is given a unique digital Certification Serial Number. Once returned to the seller, only then can it be sent to their customer in any format. There will be a PEPPOL option for this exchange of invoices. A QR Code must be included with the invoice sent to the customer.
For B2C, transactions where e-Invoices are not required by the end consumers to support the said transactions for tax purposes, suppliers will be allowed to issue a normal receipt or invoice in accordance with the current practices adopted by suppliers. After a certain period or timeframe, suppliers would be required to aggregate the normal receipts or invoices issued to end consumers and issue a consolidated e-Invoice to support the transactions made with end consumers. Further guidance on this will be provided in due course.
 This is part of a broader digitisation of tax administration. A pilot will kick-off at the start of 2024 with a phased introduction for other taxpayers during the rest of the year.
E-invoicing has been permitted in Malaysian since 2015. Both parties, the vendor and customer, must be in agreement. Electronic invoices should be retained for at least seven years.
VATCalc’s international live VAT invoice transaction and e-invoice tracker on real-time transaction-based tax reporting lists all the countries imposing transaction-based reporting.
Malaysia had introduced a full VAT regime – termed Sales and Services Taxes – between 2015 and 2018. But it returned to the old sales tax, Goods and Services Taxes. It is likely that Malaysian GST will return.

