The Netherlands has enacted the first part of its ViDA reforms
Expanding OSS from 2027 before the wider Single VAT Registration changes arrive in July 2028

The Netherlands has enacted legislation implementing the Single VAT Registration (SVR) pillar of the EU VAT in the Digital Age package. This is based on the approved EU VAT Directive implementing regulations.
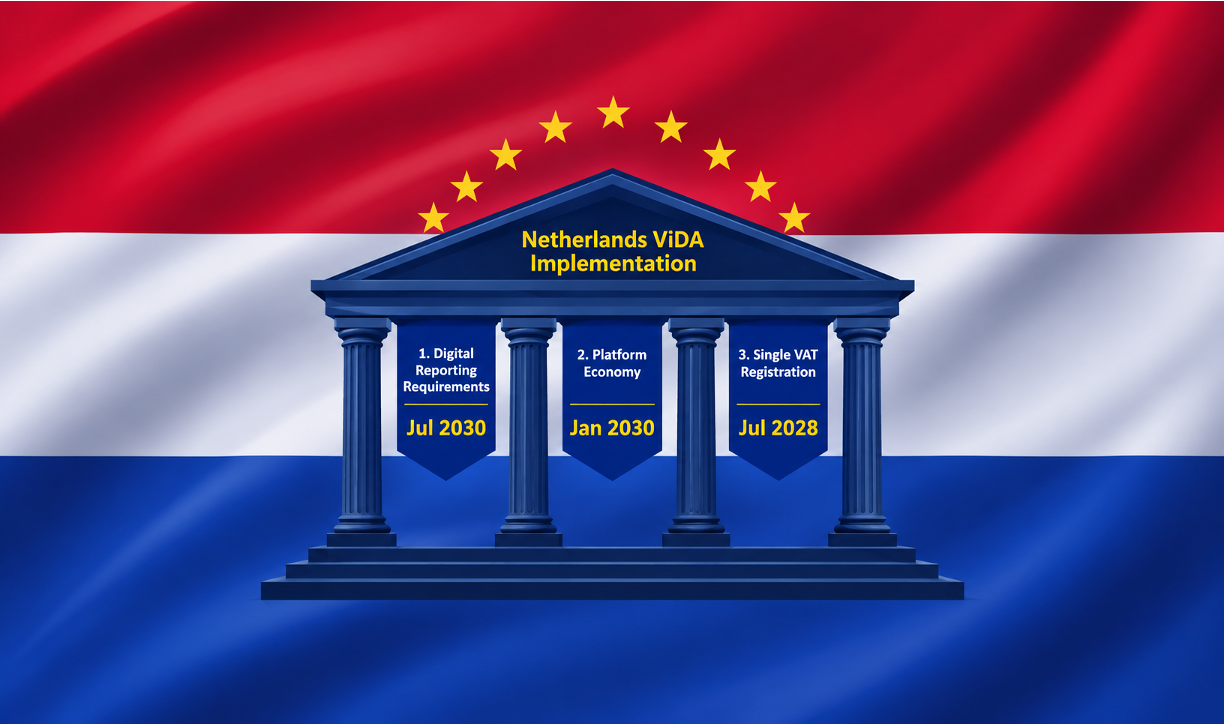
The law was signed on 7 October 2026 and published in the Dutch Official Gazette on 19 October. Initial measures take effect from 1 January 2027, followed by the main SVR reforms from 1 July 2028.
This is separate from ViDA’s mandatory e-invoicing and Digital Reporting Requirements (DRR), which take effect from 2030.
OSS starts expanding from January 2027
The first changes cover the One Stop Shop (OSS), Import One Stop Shop (IOSS) and distance-selling rules.
From January 2027, the non-EU OSS is broadened to cover all services supplied by non-EU businesses to EU consumers. There are also changes affecting electronic interfaces facilitating supplies by non-EU sellers and the calculation of the EU’s €10,000 distance-sales threshold.
For a transitional period until 30 June 2028, supplies of gas, electricity, heating and cooling are also brought within the OSS framework.
The bigger change arrives in July 2028
The main ViDA Single VAT Registration reforms apply from 1 July 2028.
OSS will expand to additional supplies of goods, including certain domestic supplies by businesses not established in the Member State of taxation. It will also cover categories such as installed or assembled goods, supplies on board ships, aircraft and trains, and energy supplies.
More significantly for businesses operating across multiple EU countries, the Netherlands will introduce ViDA’s new special scheme for transfers of own goods.
Businesses moving inventory between Member States will be able to report qualifying transfers through the scheme rather than automatically requiring a VAT registration in the destination country.
The legislation also implements the associated reverse charge for supplies by non-established businesses, further reducing circumstances in which a foreign supplier requires a local VAT registration.
Call-off stock gives way to the new regime
The existing EU call-off stock simplification will consequently be phased out.
Goods can enter the current arrangements only until 30 June 2028, with the regime finally disappearing from Dutch VAT legislation from 1 July 2029.
ViDA is therefore replacing a relatively narrow call-off stock simplification with a broader mechanism for reporting cross-border transfers of a business’s own goods.
Dutch domestic e-invoicing comes later
The Netherlands is separately preparing for mandatory B2B e-invoicing and digital reporting from 1 July 2030, covering domestic as well as intra-EU transactions.
The Dutch government announced its intended approach in September 2026 and expects the implementing proposal to be submitted to parliament before summer 2027.
So while the Single VAT Registration changes are now enacted, the Netherlands’ implementation of ViDA’s digital reporting pillar is still being developed.
Much of the attention around ViDA has focused on e-invoicing and near-real-time reporting from 2030. The Dutch legislation highlights the other side of the reform: reducing the need for businesses to maintain local VAT registrations simply because goods move or are sold across EU borders.
For businesses with multi-country EU supply chains, that may be one of ViDA’s earliest practical benefits. See more in our Netherlands country VAT guide.
EU member states ViDA implementation tracker
| Country (click for details) | Status | Latest | |
| 1 | Austria | ⚪ Awaiting legislation | - |
| 2 | Belgium | 🟠 Bill presented | OSS, distance sales, electronic interfaces and related changes |
| 3 | Bulgaria | ⚪ Awaiting legislation | - |
| 4 | Croatia | 🟠 Draft / consultation | Draft partial transposition for January 2027 |
| 5 | Cyprus | ⚪ Awaiting legislation | - |
| 6 | Czechia | 🟠 Bill in Parliament | OSS changes from January 2027 |
| 7 | Denmark | ⚪ Legislative timetable set | - |
| 8 | Estonia | 🟠 Bill before Parliament | Bill 992 SE: OSS and related changes from January 2027 |
| 9 | Finland | ⚪ Awaiting legislation | National implementation needs confirmation |
| 10 | France | ⚪ Awaiting legislation | ViDA measures notified, but first-stage position needs separating from domestic e-invoicing reforms |
| 11 | Germany | ⚪ Awaiting / monitor | - |
| 12 | Greece | ⚪ Awaiting legislation | - |
| 13 | Hungary | ⚪ Awaiting legislation | - |
| 14 | Ireland | ⚪ Awaiting legislation | - |
| 15 | Italy | 🟠 Draft legislation | Draft legislative decree – parliamentary scrutiny completed |
| 16 | Latvia | ⚪ Awaiting legislation | - |
| 17 | Lithuania | 🟢 Adopted | Law XV-1036 implements initial ViDA changes from January 2027 |
| 18 | Luxembourg | 🟠 Bill before Parliament | Bill 8812 transposes Article 2 from January 2027 |
| 19 | Malta | 🟢 Adopted | Act III of 2026 implements Article 2 from January 2027 |
| 20 | Netherlands | 🟢 Adopted | Implementation Act published October 2026; January 2027 commencement |
| 21 | Poland | 🟠 Parliamentary legislation | Bill 3074 passed Sejm; January 2027 provisions |
| 22 | Portugal | ⚪ Awaiting legislation | - |
| 23 | Romania | ⚪ Awaiting legislation | - |
| 24 | Slovakia | 🟠 Draft legislation | ViDA transposition combined with January 2027 domestic e-invoicing reforms |
| 25 | Slovenia | ⚪ Awaiting legislation | - |
| 26 | Spain | 🟠 Government legislation | Partial ViDA transposition underway in Parliament |
| 27 | Sweden | ⚪ Awaiting legislation | - |