Second wave 1 July 2026 pre-clearance E-invoicing and e-reporting mandate
The Nigerian tax authority, Federal Inland Revenue Service (FIRS) has confirmed that the second wave of e-invoicing and e-reporting will become mandatory on 1 July 2026. This is for taxpayers with annual revenues between N1 bn and N5 bn. There will be a six-month soft landing on penalties – which come effective in 2027.
Also, for the first wave, with revenues above N5bn, penalties will apply for the first time. Taxpayers will also not be able to reclaim VAT on non-e-invoices.
The first wave was November 2025. The final wave, for small enterprises, goes live July 2027.
FIRS was announced as the national Peppol Authority, on 19 October 2025 responsible for the introduce of Peppol-based invoicing in the country.
Non-resident will not become liable to report e-invoices for the time being – but FIRS will likely revisit this in 2026.
The mandate includes:
- B2B pre-clearance structured e-invoicing between businesses via the government. Businesses may use a variety of ‘Accesspoints’ to send the invoice to FIRS (same for buyers); and
- B2C transactions must be e-reported direct to FIRS within 24 hours but mandate on this to be confirmed. FIRS will return a QR code for inclusion on the B2C receipt for the buyer to validate if they wish.
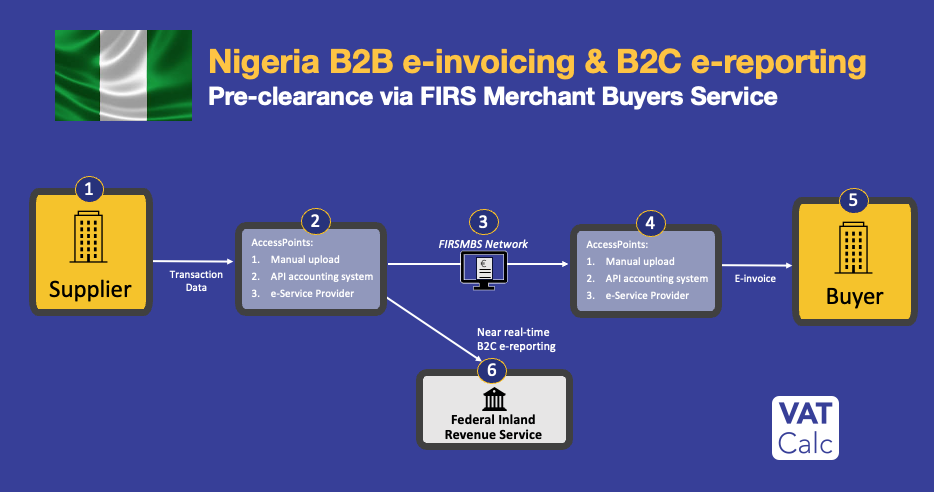
FIRSMBS Network free e-invoicing or API integration
Taxpayers may use FIRSMBS Network free e-invoice creation service at no cost, or integrate into their accounting, ERP, e-commerce or similar billing systems via an API. FIRSMBS is administered by the National Information Technology Development Agency (NITDA).
The invoices capture key transactional data, including:
- supplier and buyer information, including VAT numbers
- item descriptions,
- quantities,
- unit prices,
- applicable taxes, and
- total invoice amounts.
The technology adopted the BIS Billing 3.0 UBL standard to enable seamless exchange of e-invoices across platforms, while also streamlining business operations and tax compliance nationwide.
Each B2B e-invoice is issued a unique Invoice Reference Number (IRN). This identifier helps track, validate, and ensure that transactions are legitimate and tamper-proof, reinforcing compliance with FIRS regulations. This is supported by a QR Code for subsequent paper or PDF versions of the invoice, and scanning via app’s. Customers are then able to retrieve the e-invoices (although Suppliers may issue them with the IRN and a QR code). The Customers has 72 hours to reject the invoice.
Nigeria’s fiscal policy is at a critical juncture; the drive to expand the tax net, streamline the system and boost compliance is essential for securing Nigeria’s economic future. FIRS wants to trigger the 2007 Tax Administration and Enforcement Act to enforce digital reporting perhaps as soon as 2025. FIRS has set a target to increase tax collection by 57 per cent, targeting a revenue of N19.4 trillion for 2024.
In 2023, Nigeria’s governmental review had identified the implementation of e-invoicing as a key strategy to double VAT revenues. A form of mandatory e-invoicing is already in place with the Central Bank for clearing payments.
Check VAT Calc’s global live VAT invoice transaction and e-invoice reporting tracker to see where else real-time submissions of invoices is being implemented.
Automated Tax Administration System (ATAS)
FIRS now has the powers to implement ATAS s 30 April 2021.
ATAS enables the automation of tax investigations and audit and the collection of data. This would include access to cloud records, and outsourced accounting providers. Taxpayers would be given 30 days notice of an ATAS implementation. Refusal to allow the FIRS connect to the taxpayer’s system attracts a penalty of N25,000 in the first month and N10,000 for every subsequent month in which the default continues.
Practical questions around compatibility and integration between ATAS and taxpayer systems are not address.