B2B Peppol e-invoicing & e-reporting mandate Jan-Oct 2027
30 Oct 2026: Ministry of Finance issued Cabinet Decision No. 173 of 2026, with a new penalty regime – details below
26 Oct: Ministry issues Version 2.0 of its e-Invoicing Guidelines
21 Apr: FTA launched 4-corner model to enable taxpayers to start exchanging Peppol e-invoices.
Aside from e-invoicing, the mandate includes separate e-reporting to the FTA within days of e-invoice.

UAE mandatory e-invoicing from January 2027
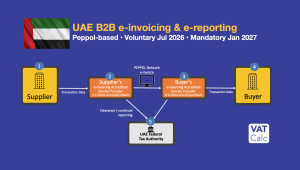
The UAE is introducing mandatory structured electronic invoicing and transaction reporting for B2B and B2G transactions.
The regime uses a decentralised five-corner Peppol model. Suppliers and customers exchange structured invoices through Accredited Service Providers, while invoice data is also transmitted electronically to the Federal Tax Authority (FTA).
A PDF sent by email will therefore not qualify as an electronic invoice. An e-invoice must contain structured data capable of being exchanged and processed electronically through the UAE system.
The UAE launched its pilot and voluntary implementation phase on 1 July 2026. Mandatory implementation is being phased according to business revenue.
| Business | Appoint ASP | Mandatory e-invoicing |
| Revenue ≥ AED 50 million | 30 October 2026 | 1 January 2027 |
| Revenue < AED 50 million | 31 March 2027 | 1 July 2027 |
| Government entities | 31 March 2027 | 1 October 2027 |
The October ASP deadline for larger businesses was extended from the original 31 July 2026 deadline. The January 2027 go-live date was not postponed.
What transactions are covered?
The regime applies broadly to persons conducting business in the UAE and covers B2B and B2G transactions, subject to specified exclusions.
Businesses in scope must appoint an ASP. Both issuers and recipients have obligations under the system, and electronic invoices and credit notes must contain the mandatory data prescribed by the Ministry of Finance.
The UAE framework is based on OpenPeppol, enabling invoices to move between businesses through accredited providers rather than through a single government clearance portal.
This is an important distinction from many other Middle Eastern and European e-invoicing models. The UAE is effectively combining decentralised Peppol invoice exchange with near-real-time reporting of invoice data to the tax authority.
October 2026 changes ease some requirements
The Ministry of Finance has made several significant changes as the regime approaches mandatory implementation.
Ministerial Decision No. 197 of 2026 provides a temporary 24-month exclusion for transactions between members of the same VAT Tax Group, starting 1 January 2027.
It also removes the requirement for e-invoice and credit-note data to be physically stored in the UAE. Businesses must instead retain the records for the required period and ensure they can be supplied to the FTA when requested.
The previous requirement to notify the FTA of an e-invoicing system failure within two business days has also been abolished.
These are practical changes, removing some of the operational requirements businesses had identified as potentially burdensome without changing the basic architecture or timetable of the regime.
UAE revises e-invoicing penalties
On 30 October, the Ministry of Finance announced a further important relaxation following stakeholder feedback.
Cabinet Decision No. 173 of 2026 replaces Cabinet Decision No. 106 of 2025 and introduces a more proportionate penalty regime.
Failure by an issuer or recipient to comply with its e-invoicing implementation obligations now attracts an initial AED 5,000 penalty, followed by AED 5,000 for each month or part of a month that the failure continues. Crucially, the aggregate penalty is capped at AED 50,000 in any consecutive 12-month period.
The previous administrative penalty for failing to notify the FTA of a system failure has also been removed, reflecting the abolition of the underlying notification obligation.
The Decision additionally prevents duplication of penalties. Where the same person acts as issuer, recipient or both in relation to the same violation, only one administrative penalty may be imposed for that violation.
Other penalties include AED 100 for each electronic invoice or electronic credit note not issued and transmitted within the required timeframe, subject to a maximum AED 5,000 per calendar month for each category.
Accredited Service Providers move into live operation
Businesses must use an Accredited Service Provider to exchange and report invoices.
The Ministry of Finance updated the ASP regime again in October through Ministerial Decision No. 168 of 2026. The earlier pre-approval model has been replaced by a full accreditation process as the UAE moves from testing into live operation.
This means ASP selection is more than an administrative deadline. Businesses must consider ERP integration, invoice data quality, Peppol connectivity, VAT determination and the reconciliation of the structured invoice data ultimately transmitted to the tax authority.
E-invoicing brings VAT determination into the transaction
The UAE model illustrates the wider shift taking place in VAT compliance.
Historically, errors in VAT determination could remain inside an ERP or accounting system until preparation of the VAT return. E-invoicing moves much of that tax data upstream. The VAT treatment applied to a transaction becomes part of structured invoice data that can be transmitted to both the customer and the tax authority.
This makes the connection between VAT determination, e-invoicing and VAT return reconciliation increasingly important.
Businesses preparing for UAE e-invoicing therefore need to look beyond whether they can technically send a Peppol invoice. They should also establish whether the underlying VAT treatment is correct and whether the invoice data can ultimately be reconciled back to their VAT reporting.
What should businesses do now?
Businesses with UAE operations should determine which implementation phase applies to them, appoint an accredited provider by the relevant deadline and assess whether their ERP and billing systems can produce the mandatory structured invoice data.
For the first wave, that process is already urgent: businesses with revenues of at least AED 50 million must be ready for mandatory e-invoicing from 1 January 2027.
VATCalc provides global VAT determination, e-invoicing, invoice validation and VAT return reconciliation through a single tax platform.